

All News Archives
Weekly Market Update for October 2, 2026
by Gavyn Jensen-Schneider, Research Associate
Treasury yields continued to climb, though a positive inflation report stemmed some of the bleeding. The S&P 500 finished the week down -0.27%, while the Nasdaq rose +0.45%. The 10-Year Treasury yield, an interest rate indicator, closed at 5.27%, up +10 basis points (bps) from last week. The 6-Month US Treasury, a favorite of our US Treasury strategy, closed at 4.29%, down -7 bps from last week.
Yields on long-dated US Treasuries jumped in September, with the 10-Year rising nearly 50 bps over the course of the month. The sudden move in Treasury rates has centered on sticky inflation and expectations of future interest rate policy. Early this week, markets were pricing in four interest rate hikes through 2026 and 2027 as investors seemed to be growing increasingly worried about inflation.
Commentary from Fed Governors this week has been mixed, with Kashkari, Barr, Logan, and others espousing the hawkish view that more work needs to be done to combat inflation. Members of the FOMC leadership—Vice Chair Jefferson and New York Fed President Williams—expressed more dovish outlooks, suggesting that more time and economic data would be needed to determine the next policy adjustment.
This week’s Core PCE inflation and employment reports give credence to the “wait and see” view. The August Core PCE inflation reading surprised to the downside at 3.0%, 30 bps lower than Wall Street expected, while the September employment report of +29k net new jobs was well below the +90k analysts expected. The unemployment rate, which crept up to 4.2% in September, hasn’t materially changed since March of this year. It remains range-bound between 4.1% and 4.3%, adding more weight to the wait-and-see approach.
Chairman Warsh has repeatedly emphasized that trends in data are more important than any single data point, and trends across inflation and employment have yet to materially change. The 3-month average Core PCE inflation remains at 3.0%, above the Fed’s 2% target, while 3-month net new jobs average remains steady at around +51k. Still, this week’s fresh data points have quelled some market woes, as Fed Funds Futures are pricing in only three hikes as of Friday.
Some additional clarity on the Fed Board’s thinking might arrive in next Wednesday’s release of the FOMC minutes. Quantitative economic data releases will otherwise be limited, with Services PMI on Tuesday and the University of Michigan Consumer Sentiment index on Friday representing the week’s most important prints. Corporate earnings will be similarly quiet as we wait for the big banks to kick off Q3 earnings season on October 13.
The information contained in this commentary is not investment advice for any person. It is presented only for informational purposes. Included information has been obtained from sources considered reliable, but we do not guarantee that the foregoing materials are accurate or complete. Investors should contact Ulland Investment Advisors for individualized information prior to deciding to participate in any portfolio or making any investment decision. Ulland Investment Advisors does not provide tax advice. All investors are strongly urged to consult with their tax advisors regarding any potential investment. Performance quoted is past performance. Past performance is not indicative of future performance. There is always a possibility of loss.
Current performance may be lower or higher than performance shown. Differences in performance versus the indices/funds may be attributable, in part, to differences in the asset make-up of the strategy vs. the indices/funds. Performance calculations are based on the reinvestment of dividends and gains unless these amounts were paid out to the client. Performance is subject to revision. See www.ullandinvestment.com for important strategy disclosures.
This does not constitute a recommendation of any investment strategy or product for a particular investor. Investing involves risk; principal loss is possible. Investors should consider the investment objectives, risk, charges, and expenses of the strategy carefully before investing. This and other important information can be obtained by contacting Ulland Investment Advisors at www.ullandinvestment.com or 612.312.1400.
Weekly Market Update for September 25, 2026
by Gavyn Jensen-Schneider, Research Associate
Technology continues to forge ahead, leading to gains for major indices. The S&P 500 finished the week up +1.21%, while the Nasdaq rose +2.06%. The 10-Year Treasury yield, an interest rate indicator, closed at 5.17%, up +17 basis points (bps) from last week. The 6-Month US Treasury, a favorite of our US Treasury strategy, closed at 4.36%, up +9 bps from last week.
The Trump-Xi summit brought much fanfare to Washington, DC this week, though specific policy accomplishments were minimal. The US and China extended their trade truce for another two months, creating additional breathing room to finalize a tariff deal. Trade Representative Greer also indicated that the two nations had reached a tariff reduction agreement on a “subset” of goods, to be detailed on September 28th. AI safety was likely a major topic behind closed doors, though the only substantive announcement was a bilateral AI safety summit to take place in November of this year.
Meta continued to capitalize on the momentum of its new personal AI agent Muse, which catapulted to the #1 AI app on the Apple App Store. At Meta Connect 2026, CEO Mark Zuckerberg unveiled the latest additions to the smart glasses’ lineup as well as a brand-new form factor: a keychain-sized, audio-activated AI assistant called Muse Charm. The stock bounced nearly 13% on the week from its AI momentum.
The Iran conflict continues to adversely affect fuel markets, with diesel prices spiking in recent weeks. US diesel was priced around $3.90 a gallon on March 2, a few days after the start of the conflict, and has risen to $6.53 a gallon as of September 21. A substantial portion of that price rise has come in September alone, as prices rose $0.93 per gallon over the course of the month, thus far.
Some respite might be in the cards, as Iranian negotiators have proposed a seven-day plan to reopen the Strait of Hormuz, mitigate economic sanctions, and rekindle nuclear talks. The US has not commented on the plan, but the warring nations seem to be having positive discussions through mediators.
The turn of the month—and end of the third quarter—means a fresh set of economic indicators. August JOLTS will be released on Tuesday, followed by the final Q2 GDP reading and August PCE inflation on Wednesday. Nonfarm payrolls and the unemployment rate close out the week on Friday. Investor conferences are plentiful as well, though OpenAI’s developer day on Tuesday is the major highlight.
The information contained in this commentary is not investment advice for any person. It is presented only for informational purposes. Included information has been obtained from sources considered reliable, but we do not guarantee that the foregoing materials are accurate or complete. Investors should contact Ulland Investment Advisors for individualized information prior to deciding to participate in any portfolio or making any investment decision. Ulland Investment Advisors does not provide tax advice. All investors are strongly urged to consult with their tax advisors regarding any potential investment. Performance quoted is past performance. Past performance is not indicative of future performance. There is always a possibility of loss.
Current performance may be lower or higher than performance shown. Differences in performance versus the indices/funds may be attributable, in part, to differences in the asset make-up of the strategy vs. the indices/funds. Performance calculations are based on the reinvestment of dividends and gains unless these amounts were paid out to the client. Performance is subject to revision. See www.ullandinvestment.com for important strategy disclosures.
This does not constitute a recommendation of any investment strategy or product for a particular investor. Investing involves risk; principal loss is possible. Investors should consider the investment objectives, risk, charges, and expenses of the strategy carefully before investing. This and other important information can be obtained by contacting Ulland Investment Advisors at www.ullandinvestment.com or 612.312.1400.
Weekly Market Update for September 18, 2026
by Gavyn Jensen-Schneider, Research Associate
Market indices waffled throughout the week. The S&P 500 finished the week down -0.08%, while the Nasdaq rose +0.72%. The 10-Year Treasury yield, an interest rate indicator, closed at 5.00%, up +3 basis points (bps) from last week. The 6-Month US Treasury, a favorite of our US Treasury strategy, closed at 4.27%, up +12 bps from last week.
The Federal Open Market Committee (FOMC) hiked interest rate policy by 25 basis points at its meeting Wednesday, bringing the rate to 3.75% – 4.00%. The unanimous decision was described as “removing a dose of accommodation” by Chairman Warsh as the FOMC was “hard pressed” to call interest rate policy restrictive. The Chairman, who has already gained a reputation for being tight-lipped, gave little new information to market watchers, only describing the labor market as stable and highlighting elevated 6- and 12-month inflation trends.
The FOMC also released its quarterly summary of economic projections (SEP), in which committee members estimate the future path of the economy and interest rates. Inflation was clearly the worry of the committee, as the median member foresaw core PCE inflation at 3.7% by the end of 2026, before steadily lowering in 2027 and 2028 to reach the Fed’s 2% target. To beat back projected inflation, 16 of 18 FOMC participants forecast another interest rate hike before the end of the year. Consistent with his dislike of forward guidance, Chairman Warsh did not provide his own interest rate “dot” estimate in the SEP.
AI safety has been gaining attention in recent weeks, reaching a fever pitch as Anthropic CEO Dario Amodei called for global coordination and an international slowdown in AI development. Amodei sees AI as an amazingly powerful tool, but believes more third-party safety evaluators, regulation and cybersecurity protocols need to be developed to keep AI aligned with its users’ goals. Other AI leaders, including Nvidia CEO Jensen Huang and OpenAI CEO Sam Altman pushed back, calling for tech leadership to self-regulate rather than bringing in government regulators. OpenAI and Anthropic have both committed to allowing independent evaluators access to company systems and models prior to their public releases.
International regulation on AI is one of many potential topics for President Donald Trump and President Xi Jinping next week as the Chinese leader visits Washington DC. Xi’s White House visit on September 24th will be the first in a decade, and the second summit of the two leaders this year. Outside of AI, the two dignitaries have much else to discuss; extending the tariff truce that began in October 2025 and expires on November 10th; locking in a deal for US agricultural and industrial goods; discussing the island of Taiwan; stemming fentanyl flows from China; and the Iranian conflict.
Trump and Xi’s Thursday meeting dwarfs the other events on next week’s calendar. A few investor day events are scheduled, including the Meta Connect event, while economic data primarily includes manufacturing and services PMI and September’s final reading of University of Michigan Consumer Sentiment.
The information contained in this commentary is not investment advice for any person. It is presented only for informational purposes. Included information has been obtained from sources considered reliable, but we do not guarantee that the foregoing materials are accurate or complete. Investors should contact Ulland Investment Advisors for individualized information prior to deciding to participate in any portfolio or making any investment decision. Ulland Investment Advisors does not provide tax advice. All investors are strongly urged to consult with their tax advisors regarding any potential investment. Performance quoted is past performance. Past performance is not indicative of future performance. There is always a possibility of loss.
Current performance may be lower or higher than performance shown. Differences in performance versus the indices/funds may be attributable, in part, to differences in the asset make-up of the strategy vs. the indices/funds. Performance calculations are based on the reinvestment of dividends and gains unless these amounts were paid out to the client. Performance is subject to revision. See www.ullandinvestment.com for important strategy disclosures.
This does not constitute a recommendation of any investment strategy or product for a particular investor. Investing involves risk; principal loss is possible. Investors should consider the investment objectives, risk, charges, and expenses of the strategy carefully before investing. This and other important information can be obtained by contacting Ulland Investment Advisors at www.ullandinvestment.com or 612.312.1400.
Ulland named to Broadridge’s Top 40 — across three SMA strategies
A quick and proud note for this month.
Three of our SMA strategies were recently (June) named to Broadridge’s Top 40 Money Managers (powered by Lipper) for the 12 quarters ended March 31, 2026.
Our strategy fact sheets are here:
- Intelligent Fixed Income (Preferred Stock)
- Intelligent Blend (U.S. Equity)
- Intelligent Fixed Income Gov (Treasury)
- Defensive Growth (Multi Asset Class)
Want to connect? Let’s Talk: Schedule an Intro Meeting.
Summer is here, enjoy it! -Nat
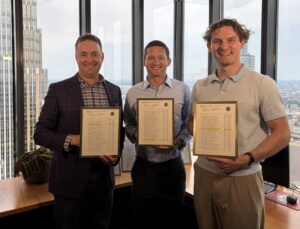
Please click the strategy name to view the full Top 40 list for each strategy.
- Intelligent Fixed Income — #5 of 1,032 in the U.S. Fixed Income (All Styles) category | $192.3M AUM
- Defensive Growth — #15 of 333 in the U.S. Balanced/Multi-Asset (All Styles) category | $151.1M AUM
- Intelligent Blend — #37 of 246 in the U.S. Diversified/Multi-Cap Equity category | $38.9M AUM
Ranking source: Broadridge MarketPlace (powered by Lipper), Top 40 Money Managers, for the 12 quarters ended 3/31/2026, based on net-of-fee composite returns. Strategy assets as of 3/31/2026. Rankings reflect past performance and are not indicative of future results.
No compensation has been provided directly or indirectly by Ulland Investment Advisors, LLC in connection with obtaining or using the third-party rating. Rankings were released on 6/1/2026.
Best Money Managers is a comprehensive survey of institutional money managers’ performance. All rankings in this publication have met the following requirements:
• Performance must be calculated “net” of all fees and brokerage commissions. This means after all fees and commissions have been deducted;
• Performance must be calculated inclusive of all cash reserves;
• Performance results must be calculated in U.S. dollars, that is, from the perspective of a U.S.-based investor;
• Performance results must be calculated on an asset base which is at least $10 million in size for traditional” U.S. asset classes (equity, fixed income, balanced accounts) or at least $1 million in the case of international and “alternative” U.S. asset classes;
• The classification of the product must fall into one of the categories which Broadridge ranks. Broadridge only publishes rankings for categories/time period combinations for which Broadridge has at least 20 contenders.
Best Money Managers is published quarterly. While Best Money Managers acts only in a reporting capacity, every effort has been made to ensure the accuracy of the information. The “BROADRIDGE Best Money Managers, powered by Lipper” ranks investment managers against peers that have submitted performance history to the Broadridge/Lipper Marketplace database. Performance rankings are available for the most recent quarter, 4 quarter, 12 quarter, 20 quarter and 40 quarter periods. Investment managers are ranked by investment strategy performance relative to peers. Broadridge rankings are not intended to constitute investment advice or predict future results. Rankings are generally based upon information prepared and submitted by advisers. Please visit the Broadridge Marketplace website (https://marketplace.broadridge.com/marketplace) for more details about the “BROADRIDGE Best Money Managers, Powered by Lipper” rankings.
The information contained in this commentary is not investment advice for any person. It is presented only for informational purposes. Included information has been obtained from sources considered reliable, but we do not guarantee that the foregoing materials are accurate or complete. Investors should contact Ulland Investment Advisors for individualized information prior to deciding to participate in any portfolio or making any investment decision. Ulland Investment Advisors does not provide tax advice. All investors are strongly urged to consult with their tax advisors regarding any potential investment.
Performance quoted is past performance. Past performance is not indicative of future performance. There is always a possibility of loss. Current performance may be lower or higher than performance shown. Differences in performance versus the indices/funds may be attributable, in part, to differences in the asset make-up of the strategy vs. the indices/funds. Performance calculations are based on the reinvestment of dividends and gains unless these amounts were paid out to the client. Performance is subject to revision. See www.ullandinvestment.com for important strategy disclosures.
This does not constitute a recommendation of any investment strategy or product for a particular investor. Investing involves risk; principal loss is possible. Investors should consider the investment objectives, risk, charges, and expenses of the strategy carefully before investing. This and other important information can be obtained by contacting Ulland Investment Advisors at www.ullandinvestment.com or 612.312.1400.
6/5/2026
 Posted in All News

